Sample cargo customs declaration: how to read the boxes of an import declaration?
A sample cargo customs declaration (form TD 1) filled in with fictional data: what goes in each box, which classifier the codes come from, and how the customs payments in box 47 are calculated. The blank form and the sample can be downloaded as PDF.
When an importer's accountant takes goods onto the books, they rely on the cargo customs declaration (CCD, BYD in Uzbek): it shows the value of the goods, the currency, and the duty and VAT paid. But the form has 54 boxes, and at first sight it is hard to know where to look. Below is a sample filled in with fictional data: one office monitor is delivered by road from a hypothetical exporter in Turkey to a hypothetical importer in Tashkent.
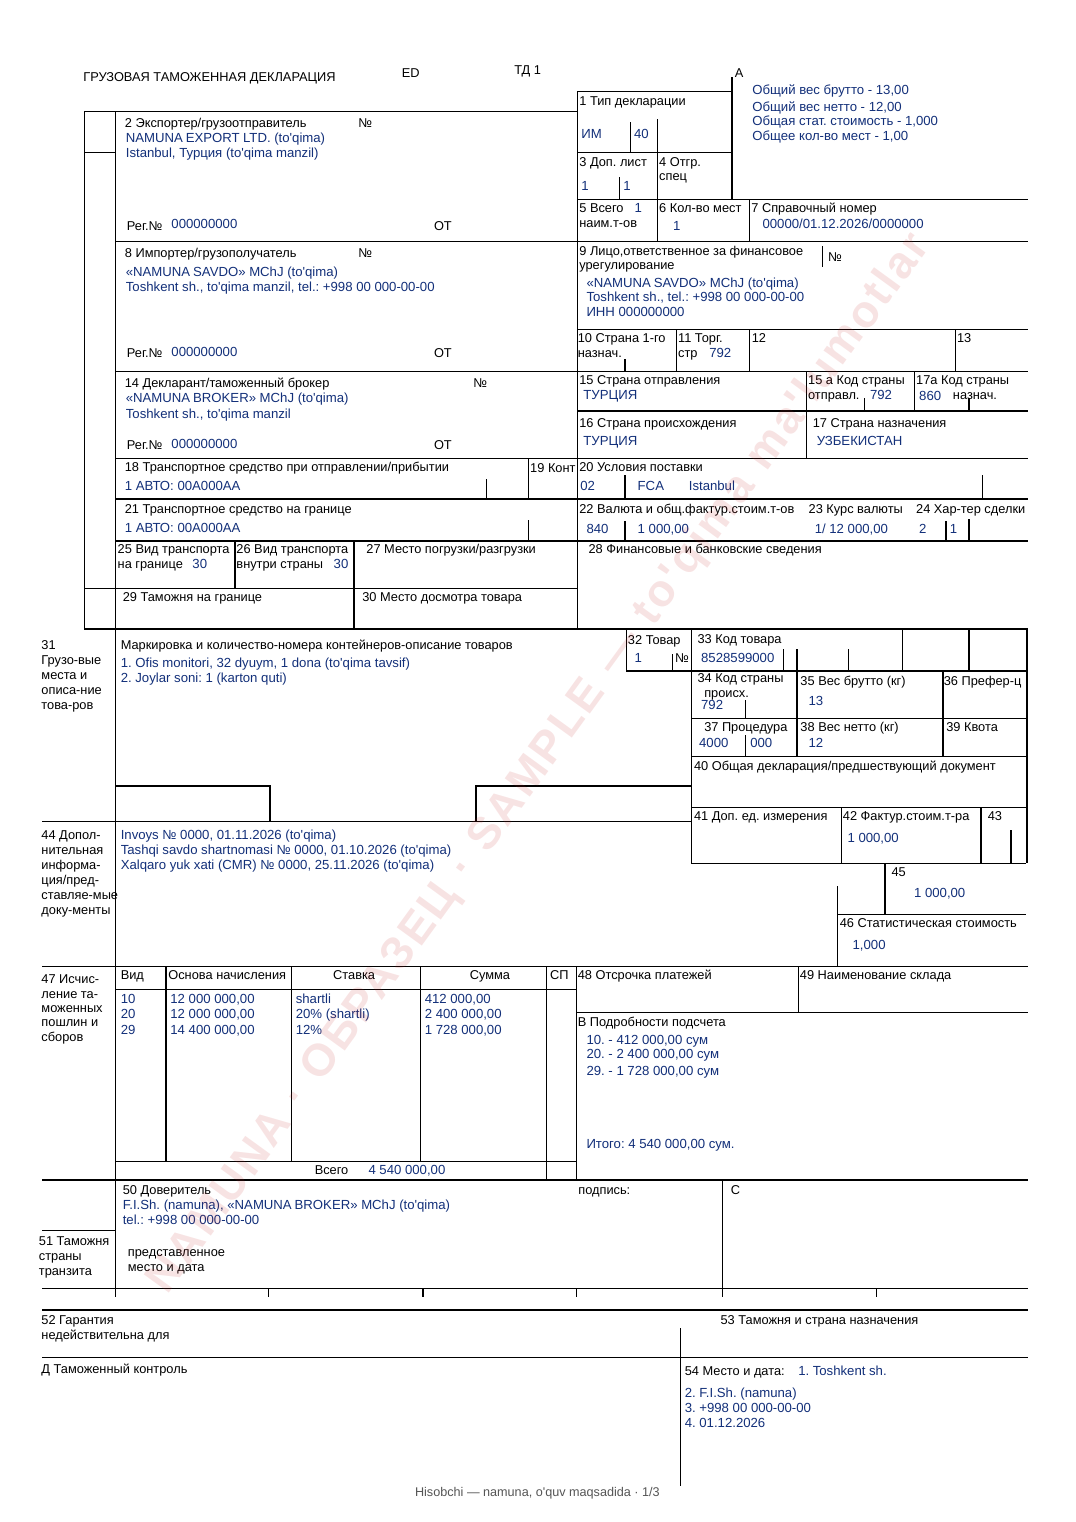
Click the image to enlarge it. The blank form and the annotated sample in PDF are in the links at the bottom of the page. The box names on the form are left in Russian, as on the official form.
How is the form structured?
Grouping the boxes makes the form much easier to read (grouping by the author):
| Group | Boxes | What it tells you |
|---|---|---|
| Declaration type | 1, 3–7 | Which procedure (IM 40 in the sample), number of sheets, item names and packages, reference number |
| Parties | 2, 8, 9, 14 | Exporter, importer, person responsible for financial settlement, declarant or broker |
| Countries and route | 11, 15–21, 25–26, 29–30 | From where, to where, by which transport, under which delivery term |
| Money | 22–24, 28 | Currency and total invoice amount, exchange rate, nature of transaction, bank details |
| Goods | 31–46 | Description, HS (TN VED) code, weight, procedure, documents, invoice, customs and statistical value |
| Payments | 47, 48, B | Base, rate and amount of each customs payment |
| Responsibility | 50, 54 | Who filled it in, where and when |
Key boxes in the sample
| Box | In the sample | Explanation |
|---|---|---|
| 1 | IM 40 | Import; 40 is the "Release for free circulation" procedure (Appendix 3 to the Instruction) |
| 11, 15 a, 34 | 792 | Code of Turkey (Appendix 5) |
| 17 a | 860 | Code of Uzbekistan (Appendix 5) |
| 20 | 02 FCA Istanbul | "Free Carrier" term (Appendix 7) |
| 22 | 840, 1 000.00 | US dollar (Appendix 8), invoice amount |
| 23 | 12 000.00 | Illustrative rate: 1 dollar = 12 000 soum |
| 24 | 21 | Movement based on settlements in foreign currency (Appendix 9) |
| 25, 26 | 30 | Road transport (Appendix 6) |
| 33 | 8528599000 | Commodity code (HS, TN VED); for real goods the correct code is determined separately |
| 35, 38 | 13 and 12 | Gross and net weight, kg |
| 45 | 1 000.00 | Customs value, in dollars |
| 47 | 10, 20, 29 | Payment types (Appendix 13) |
In the sample the customs value is taken as equal to the invoice amount: transport, loading and insurance costs are assumed to be included in the price. If they were paid separately, under Article 304 of the Customs Code they are added to the transaction price, and the customs value increases.
Box 47: how were the payments calculated?
Customs value in soum: 1 000 × 12 000 = 12 000 000 soum.
| Code | Payment (Appendix 13) | Base, soum | Rate | Amount, soum |
|---|---|---|---|---|
| 10 | Customs fees for customs clearance of goods | 12 000 000 | illustrative | 412 000 |
| 20 | Import customs duty | 12 000 000 | 20% (illustrative) | 2 400 000 |
| 29 | Value added tax | 14 400 000 | 12% | 1 728 000 |
| Total | 4 540 000 |
In the sample the VAT base is the sum of the customs value and the import duty: 12 000 000 + 2 400 000 = 14 400 000 soum. The fee is not included in it.
For the accountant: what will the cost of the goods be?
Under paragraph 15 of NAS No. 4, customs duties and fees are included in the cost of inventories, and under paragraph 24 the foreign-currency value is translated into soum based on the value in the CCD at the Central Bank rate on the date the goods are recognised. With the illustrative figures of the sample:
| Cost components | Amount, soum |
|---|---|
| Value of goods in soum (1 000 × 12 000) | 12 000 000 |
| Customs fee | 412 000 |
| Import customs duty | 2 400 000 |
| Cost | 14 812 000 |
If the company has chosen to carry goods bought solely for resale at purchase value, under paragraph 30 the duty and the fee go not into cost but into period expenses. Consider the accounting for import VAT separately, depending on your company's tax regime.
Practical tips
- As soon as the CCD arrives, check boxes 22, 23 and 45 against the invoice and the contract: the amount, currency and quantity of goods must match.
- Check every amount in box 47 against the amounts paid through the bank.
- Keep the cost calculation together with the CCD number and date: it is the first document requested in an inspection.
Test yourself
5 questions on this topic: pick an option or reveal the answer.
A sewing factory imported fabric from abroad for production. According to the cargo customs declaration, the purchase cost at the exchange rate on the date of recognition is 80 000 000 soum. Additional costs: customs duties and fees 6 000 000, freight 3 000 000, certification and testing 1 000 000, bank commission for currency exchange 500 000 soum (amounts are hypothetical; import VAT is accepted for offset and is not shown in this example). Under NAS No. 4, what is the cost of the fabric?
Code 71 is entered in the mode-of-transport box of a cargo customs declaration. Which mode of transport does this code denote?
VAT payer "Nurafshon metall" made products from a foreign customer's raw material placed under the processing within the customs territory procedure. The service fee excluding VAT is 45,000,000 soums. The products were not taken out: the customer placed them under the release for free circulation (import) procedure. How much VAT is charged on the service fee?
Which code is used in the cargo customs declaration to indicate the "Customs warehouse" customs regime?
Under Article 259 of the Customs Code, who fills in the passenger customs declaration and for what goods?
Answered: 0 / 50 of 5 correct
All tests →See also
Sources
- Instruction on the procedure for filling in the cargo customs declaration (registered by the Ministry of Justice under No. 2773), Appendices 3, 5, 6, 7, 8, 9 and 13 · codes for the procedure (40), countries (792, 860), transport (30), delivery terms (02 FCA), currency (840), nature of transaction (21), payment type (10, 20, 29)
- Customs Code of the Republic of Uzbekistan, Article 304 · transport, loading and insurance costs added to the transaction price
- NAS No. 4 "Inventories", paragraphs 15, 24 and 30 · customs duties and fees are included in cost; translation of the purchase value in foreign currency; option to carry goods for resale at purchase value
- Sample declaration, company names, numbers, exchange rate, duty rate and fee amount · compiled by the author, fictional and illustrative